 OnBinder
Social
A short written take on each piece of content: what changed and why it matters. Skim the point first, then follow through to the full article only for what interests you. Every take is drawn from real content, so the link takes you straight to the material it is based on.
7 Rules for Growing Wealth: Conditions and Pitfalls of Ownership, Compounding, and Leverage
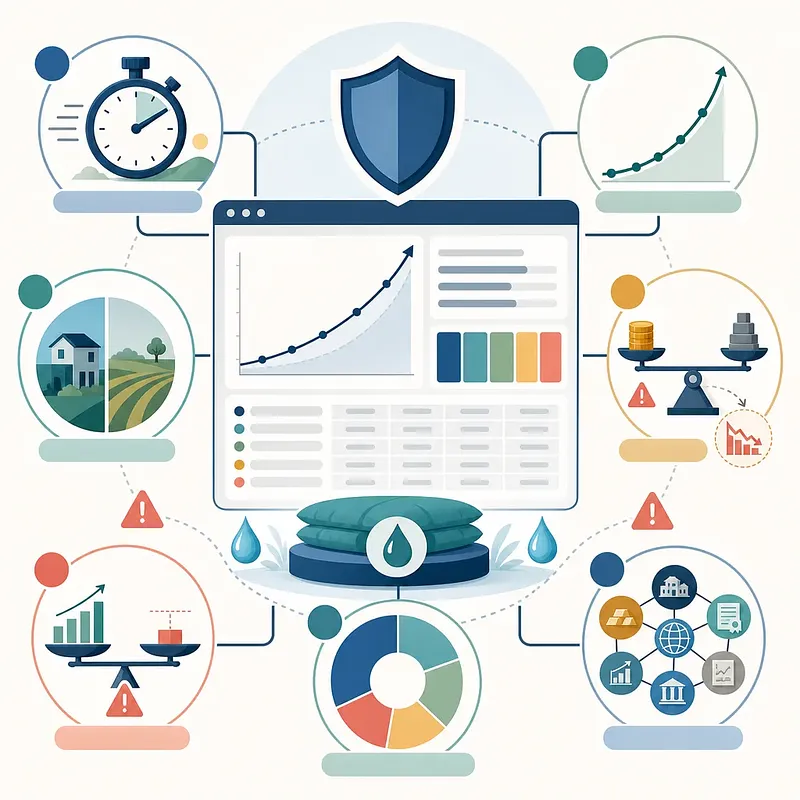
Popular wealth-building principles are often presented through success stories, but each depends on conditions that are easy to overlook. Long-term ownership can support compounding only when the underlying asset produces real value and remains financially durable. A minority economic stake is also different from the control required to direct a business. Meanwhile, leverage raises more than return on equity: it increases losses, interest obligations, liquidity pressure, and the risk of forced sales. This article brings seven principles into one risk-management framework, including how to assess asymmetric rewards through loss limits and probability—not maximum upside alone. It also explains why asset allocation, diversification, cash reserves, and liquidity management are central to long-term survival. #RiskManagement #AssetAllocation #Investing
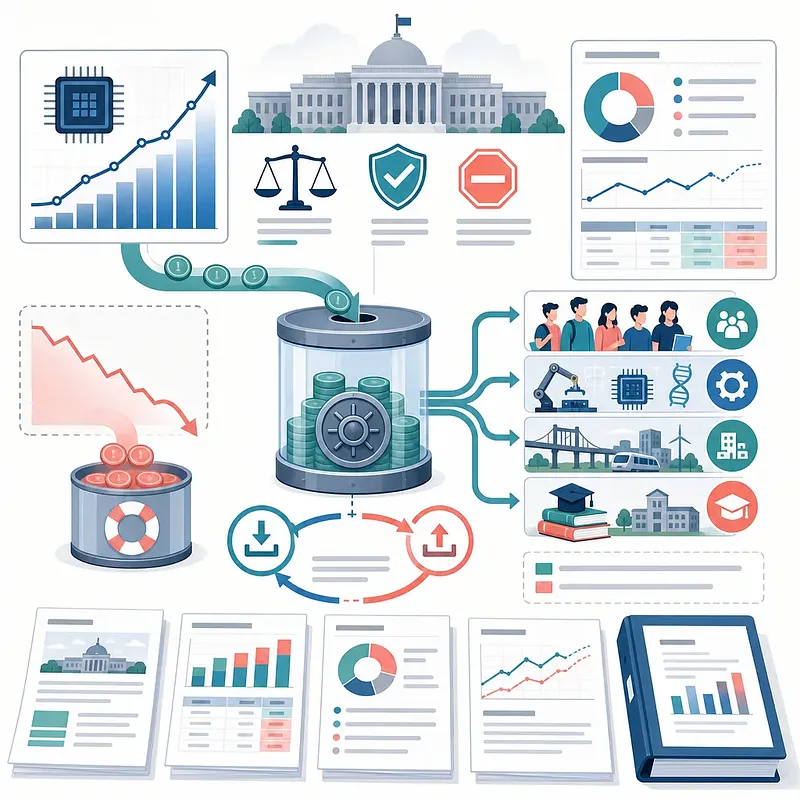
The Future Response Fund proposal could turn a portion of tax revenue collected above forecasts—including revenue associated with the semiconductor boom—into a source of long-term investment and fiscal stabilization. Why it matters: the frequently cited fund sizes of 60–70 trillion won or around 100 trillion won are projections, not finalized commitments. Specific allocations for youth, growth engines, local regions, education, and talent will depend on the official bill and fund management plan. Effective governance will also require clear accumulation and withdrawal criteria, controls on plan changes and overlapping programs, performance evaluation, loss management, and rules for terminating unsuccessful initiatives. The article separates the proposal’s stated direction from the details that still need confirmation. #PublicFinance #FiscalPolicy
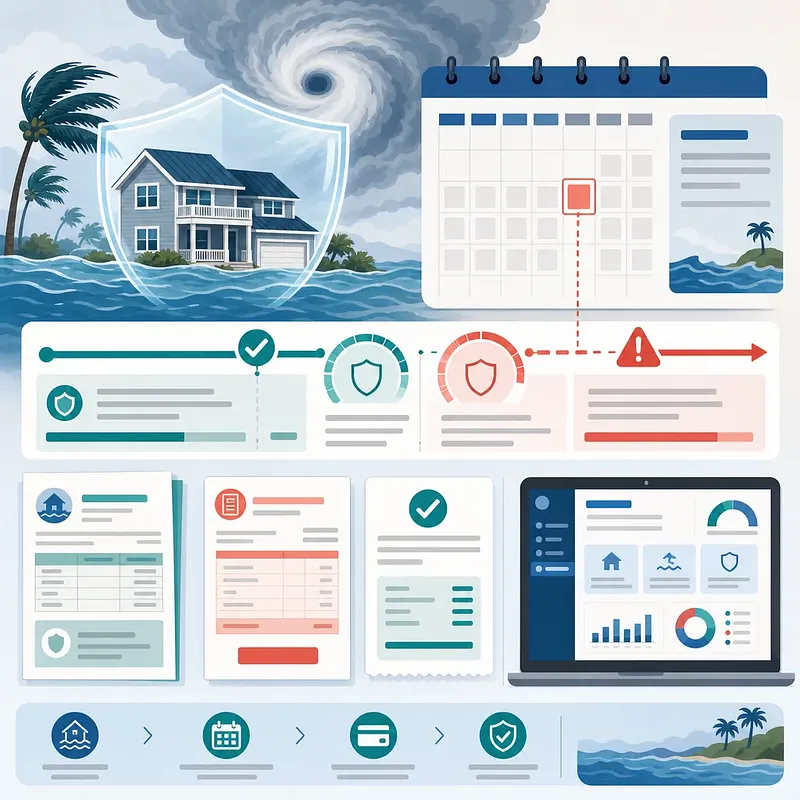
NFIP policyholders must renew manually. Pay early enough for the full premium to be received before expiration rather than relying on the 30-day grace period. The coverage outcome can differ between a renewal paid in full during that grace period and a new policy purchased after the original coverage has lapsed. A new application may also be subject to a 30-day waiting period. The article lays out how to verify the expiration date, insurer and Direct status. Direct customers can prepare their policy number and renewal bill ID, while other customers can identify the insurer or agent they need to contact. This creates a clearer path to confirming premium receipt and reducing coverage-gap risk. Policyholders with expired coverage should first determine whether they are still within 30 days and ask whether renewal remains available. Those dealing with a lapse can also review the mortgage, hazard map and wildfire exceptions before deciding what to do next. Read the article for the complete process. #NFIP #FloodInsurance
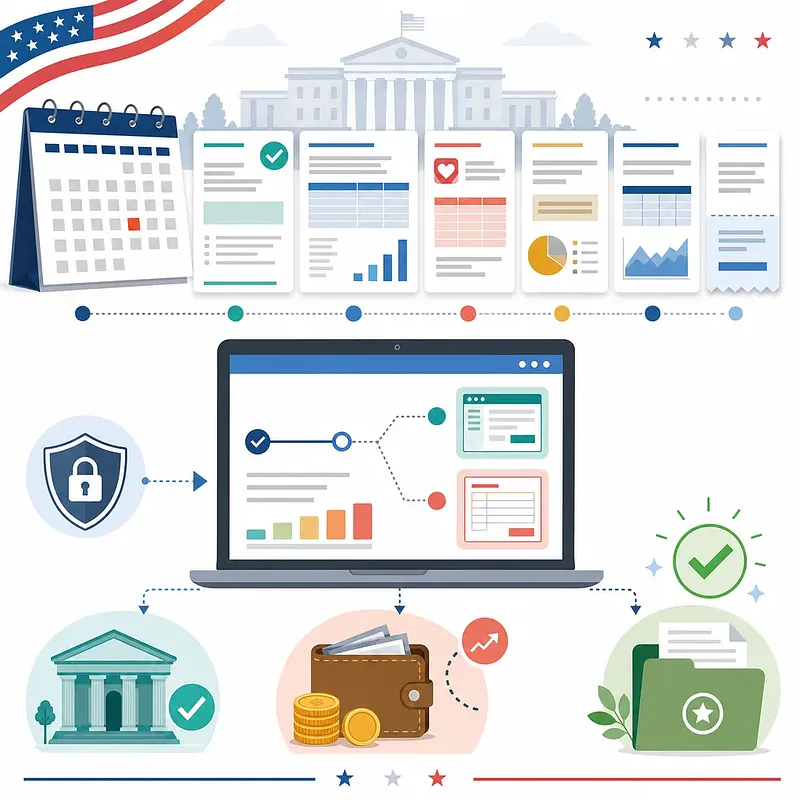
Taxpayers who extended their 2025 U.S. federal income tax return generally need to file by October 15, 2026—but the first step is verifying the extension through a Form 4868 record or electronic payment confirmation. This practical guide outlines the documents to prepare, including W-2s, 1099s, Form 1095-A, prior-year returns, IRS tax records, and refund account information. It also explains the 2025 AGI threshold of $89,000 for IRS Free File guided software and other filing options for higher incomes. Because an extension to file is not an extension to pay, the guide also addresses unpaid tax, accrued interest and penalties, and the importance of confirming IRS acceptance after electronic filing. #TaxFiling #Taxes
8.13 Three-Part Youth Housing Support Package: Homeownership, Semi-Jeonse, Jeonse, and Risks to Check
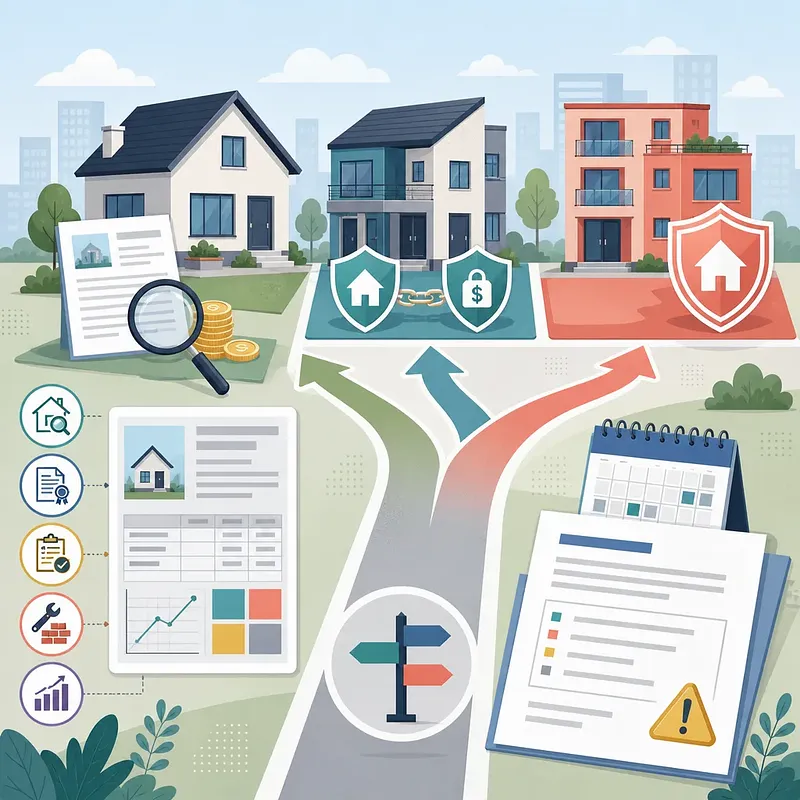
Korea’s August 13 proposal introduces three forms of youth housing finance support: a homeownership loan, a combined guarantee for semi-jeonse and monthly rent, and expanded special youth jeonse loan guarantees. For prospective buyers, the distinction between policy benefits and property risk matters. The proposed Youth Future Bogeumjari Loan targets people aged 39 or younger with annual income of KRW 70 million or less who buy qualifying non-apartment homes priced at KRW 400 million or less. However, the interest rate, LTV margin, fees, income calculation, and application process remain subject to final announcements. The article reviews proposed eligibility, an illustrative repayment calculation, and essential due diligence for non-apartment purchases. #HousingPolicy #RealEstate
Principles for Designing Dividend Investments for Retirement Cash Flow
Dividend investing can contribute to retirement cash flow, but neither distributions nor principal are guaranteed. That makes portfolio design more important than simply selecting the highest yields. A rising yield may reflect a declining share price or increased risk of a dividend cut. Investors should evaluate payout capacity using both earnings and free cash flow, while also considering debt, competitive strength, and industry-specific capital structures. Dividend ETFs can simplify diversification, but their index methodology, costs, concentration, and distribution composition still require review. For retirement planning, combining dividends with pensions, interest, cash equivalents, and selective asset sales may create a more resilient approach aligned with actual spending needs. #AssetAllocation #Diversification #RetirementPlanning