 OnBinder
Social
A short written take on each piece of content: what changed and why it matters. Skim the point first, then follow through to the full article only for what interests you. Every take is drawn from real content, so the link takes you straight to the material it is based on.
How Small-Scale Sole Proprietors Can Apply for the 2026 Special Tax Arrears Collection Provision
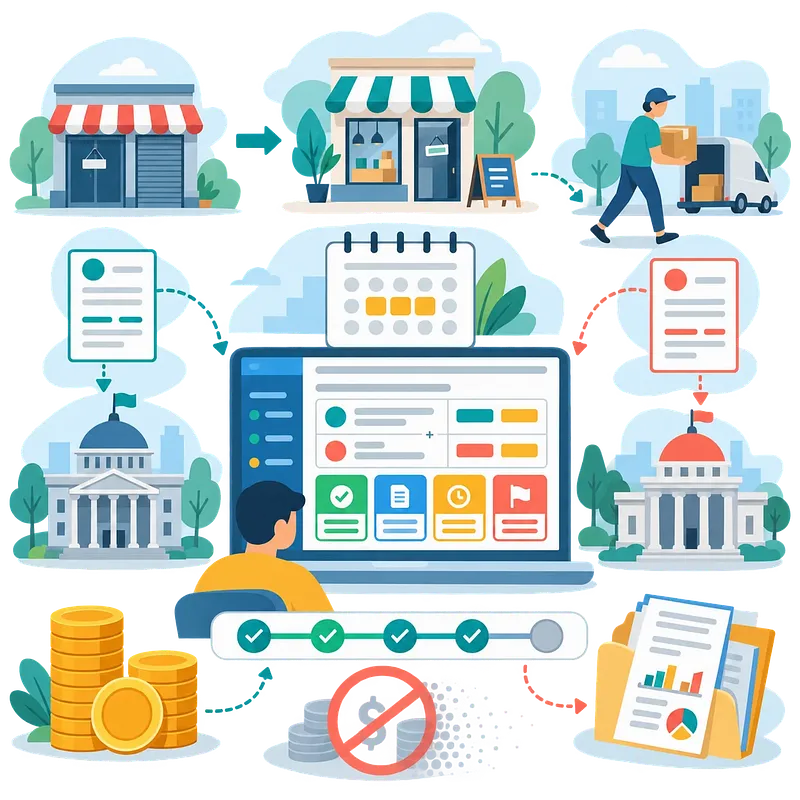
Your tax arrears reach KRW 80 million. At or below that cap, eligible sole proprietors may receive late-payment penalty exemption and up to five years to pay principal. The restart rule changes for applications filed on or after April 1, 2026. Workers in special forms of employment who have provided labor for at least three months may also qualify under this requirement, subject to the other conditions. The article explains how to combine comprehensive income tax and VAT arrears in Hometax, confirm the tax office responsible for each amount, and assess the closure date, average revenue for the three tax years before closure, and restart period. It also covers the identification, registration, employment, and labor-provision documents used to establish closure and restart. Small-scale sole proprietors considering this provision should also note that arrears handled by two or more tax offices require separate applications by jurisdiction. Read the guide to understand the filing channels and the steps for paying principal under an approved installment schedule. #SoleProprietor #TaxFiling
How to Apply for Cheongdo County's 2026 Small Business Card Fee Support and Revised Criteria
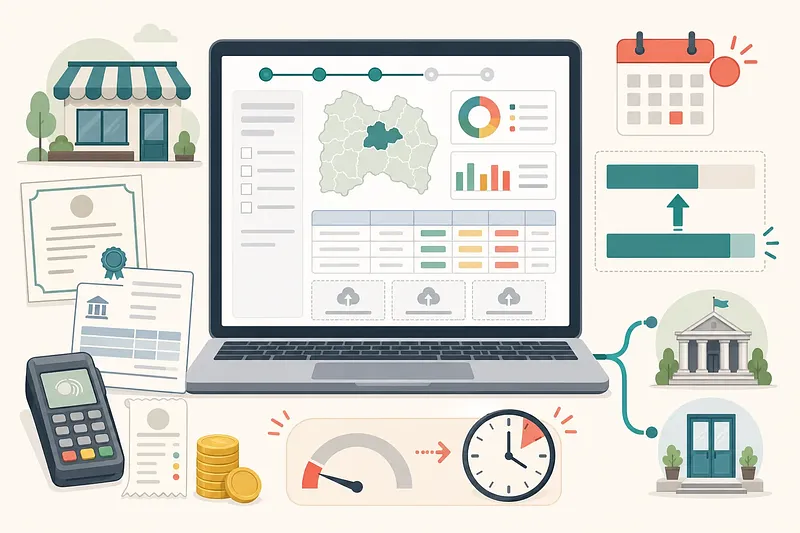
The sales cap is now KRW 300 million. Cheongdo County’s revised September 3, 2026 announcement expands the 2025 sales threshold from KRW 200 million to KRW 300 million. This change may matter to businesses that were previously rejected because their sales exceeded the former cap. Meeting the expanded threshold does not itself confirm eligibility, so applicants should also verify the business location on their registration certificate and whether the business qualifies as a small business. The article outlines the required business registration, identity, and deposit account materials. It also explains how to select Cheongdo County and apply through Haengbok Card, where to submit documents in person, and how to check the Application Results menu while retaining the application number or completion screen. Cheongdo County small businesses considering an application or a reapplication inquiry should read the guide first. The program may close early if its budget is exhausted, and applicants previously denied under the old cap should inquire whether reapplication is possible. #SmallBusiness #CardFeeSupport
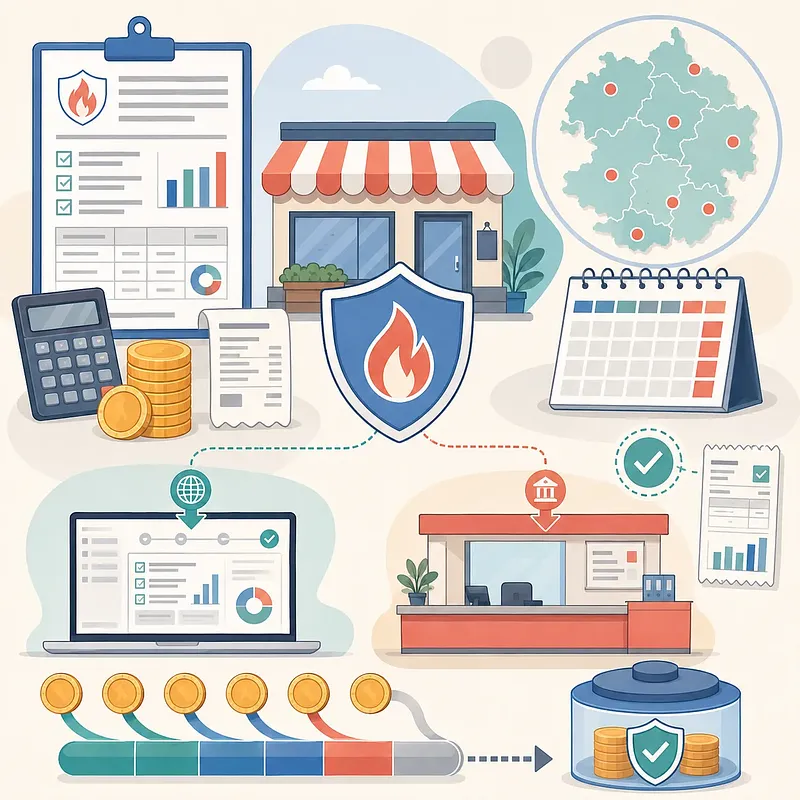
A Chungnam application needs review. Eligible firms can apply for support covering 80% of coverage premiums, up to KRW 240,000 per year, by September 30, 2026. The calculation is based on the coverage premium shown on the insurance statement; any savings premium is excluded. That distinction can change the amount you expect and the supporting records you prepare. The article maps both submission routes: online through Small Business 24 and in person at the city or county office where the business is located. It also covers the attached forms, policy and premium-payment evidence, submission confirmation, additional-information requests, and final decision notice, helping applicants organize each stage. Small businesses operating in Cheonan, Gongju, Asan, Seosan, Dangjin, Geumsan, Cheongyang, or Yesan and maintaining fire insurance in 2026 should read the guide before applying. #SmallBusiness #FireInsurance
How to Apply for the First-Half 2026 Earned Income Tax Credit and Eligibility Requirements
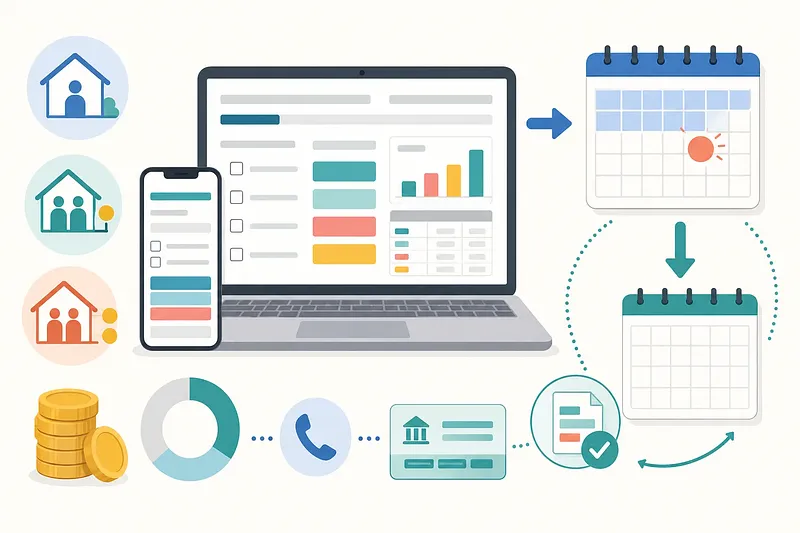
A 35% payment may be made in December. For first-half 2026 Earned Income Tax Credit applicants, that is 35% of the estimated annual amount after review. The application deadline is September 15, 2026. Eligibility begins with the source of income. The applicant and spouse must have earned only employment income during the first half of 2026. The guide explains how to consult National Tax Service guidance for the relevant income threshold by household type and the asset valuation reference date, supporting a more informed eligibility check before filing. Applicants can use Hometax, mobile Hometax, or ARS at 1544-9944. The article also outlines what to verify afterward: the application result, bank account information, the potential December payment, and the following year’s reconciliation. Households meeting the employment-income condition should read the article before applying to understand the criteria, filing routes, and post-application process. #EarnedIncomeTaxCredit #Hometax
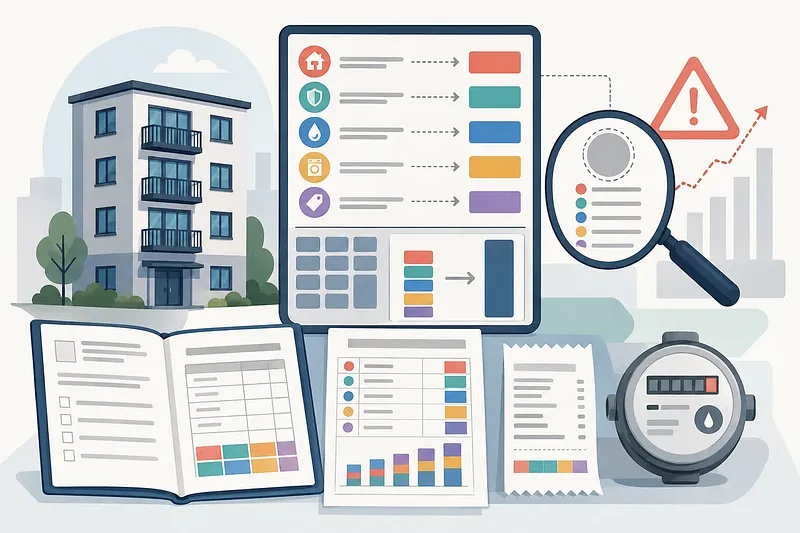
Before signing, price every extra. Advertised monthly rent is only one part of the actual housing cost. Maintenance fees, utilities, and option usage fees should be included in an average monthly total before making a contract decision. Opaque fee labels can hide different charging methods. Fixed, usage-based, and one-time costs need separate calculation bases, so the headline rent alone may not provide a reliable comparison between properties. The article outlines a practical approach: record the agreed fee items, settlement method, and process for receiving supporting documents in a special contract clause. After moving in, compare that clause with each maintenance bill, meter reading, and payment receipt. This provides a clearer basis for requesting written explanations when charges increase without supporting records. Prospective monthly renters and tenants reviewing post-move charges should read the article to assess their total housing costs and understand when an authority or dispute resolution procedure may be appropriate. #HousingLease #RentalCosts
Storm, Flood, and Earthquake Disaster Insurance Subsidy Rates and Coverage to Check During a Typhoon Alert
Premium subsidies range from 55–100%. For eligible disaster insurance, this support can reduce the premium paid by the policyholder, but the precise rate depends on the property type, vulnerable-group status, and additional local government support. That variation makes it important to confirm the applicable rate with the relevant local government and participating insurer rather than relying on the maximum figure alone. The article outlines coverage for direct property damage caused by typhoons, floods, heavy rain, strong winds, high waves, storm surges, heavy snow, earthquakes, and tsunamis. It also explains how the insured property, insured amount, deductible, compensation method, and exclusions affect payouts, helping readers assess a policy beyond its subsidy rate. Owners of eligible homes and contents, agricultural or forestry greenhouses, and small-business shops or factories should read the guide first. It also clarifies why a new policy cannot retroactively cover earlier damage or a disaster already underway. #DisasterPreparedness #RiskManagement