 OnBinder
Social
A short written take on each piece of content: what changed and why it matters. Skim the point first, then follow through to the full article only for what interests you. Every take is drawn from real content, so the link takes you straight to the material it is based on.
Proposal for Interest on Refunded IPO Subscription Deposits: Calculation and Issues to Review
Financial authorities are reportedly considering interest payments on IPO subscription deposits returned after share allocations are settled. The proposal could affect how investors evaluate the cost of temporarily placing funds with brokerage firms. However, key details—including the interest rate, eligible amount, calculation dates, weekends, taxes and costs—have not been finalized. A theoretical scenario using a 1% annual rate and a three-day holding period produces a sizable aggregate estimate, but it is not a confirmed payment amount. Investors should also compare potential interest with IPO subscription loan costs. Read more : https://injoys.com/en/articles/ipo-subscription-deposit-refund-interest-korea #IPO #CapitalMarkets
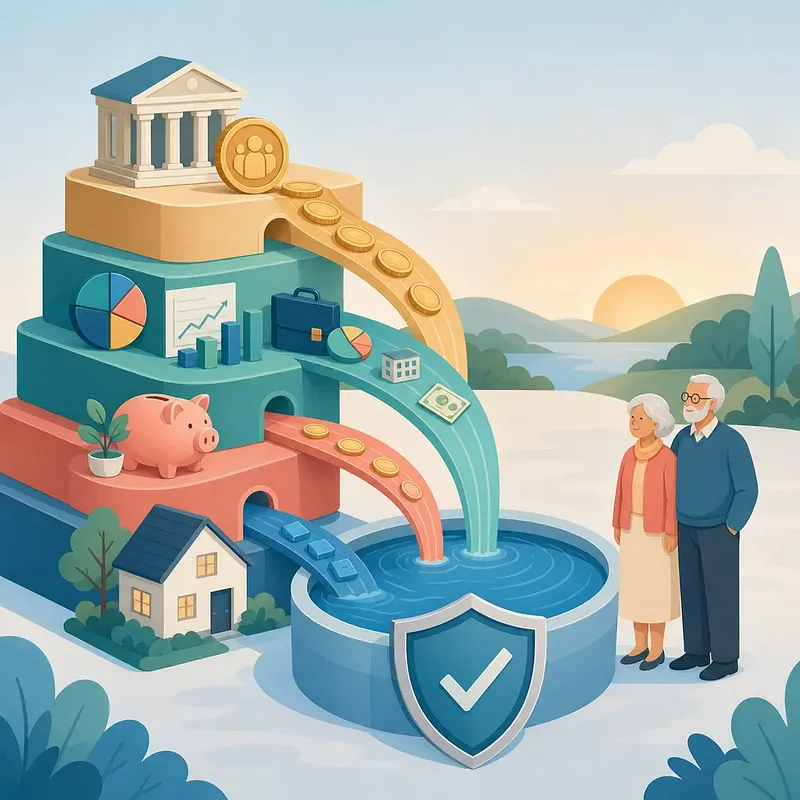
A strong retirement strategy should focus on sustainable monthly cash flow, not only total assets. Choosing when to claim the National Pension is one part of that strategy. Claiming five years early reduces the monthly benefit by 30%, while deferring for five years increases it by 36%. However, break-even points vary with the options and assumptions being compared, so health, income, assets, and life expectancy all matter. This article outlines a four-tier approach using the National Pension, retirement pension, personal pension, and reverse mortgage. It also covers make-up contribution requirements and why receiving IRP retirement benefits as a pension may reduce the retirement income tax burden compared with a lump sum. Read more : https://injoys.com/en/articles/korea-four-layer-retirement-pension-strategy #RetirementPlanning #Pensions
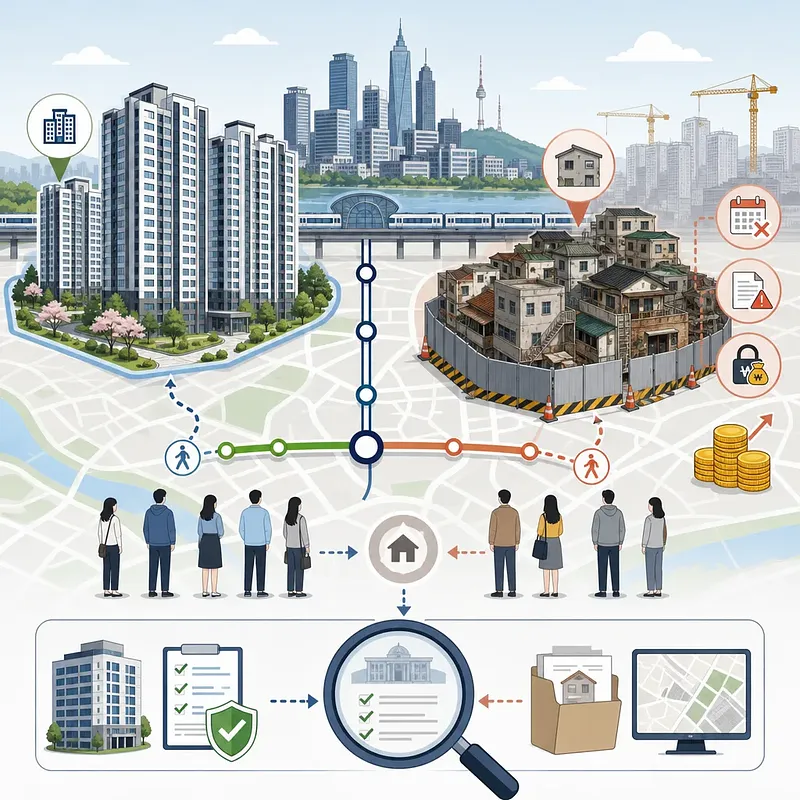
Loan restrictions can affect purchasing power, but they do not determine the direction of home prices on their own. Interest rates, household income, housing supply, the jeonse market, and regional demand also matter. A disciplined buying decision combines repayment capacity with property-level verification. Monthly principal and interest of no more than 30% of after-tax income may serve as a conservative reference—not a statutory limit. Buyers should also compare real travel times to business districts, transfers, complex size, floor plans, transaction volume, and total transaction costs. The article also outlines key checks for trading up, redevelopment properties, and homes with existing jeonse tenants using official transaction, project, and loan data. Read more : https://injoys.com/en/articles/korea-home-buying-under-loan-restrictions #HomeBuying #RealEstate
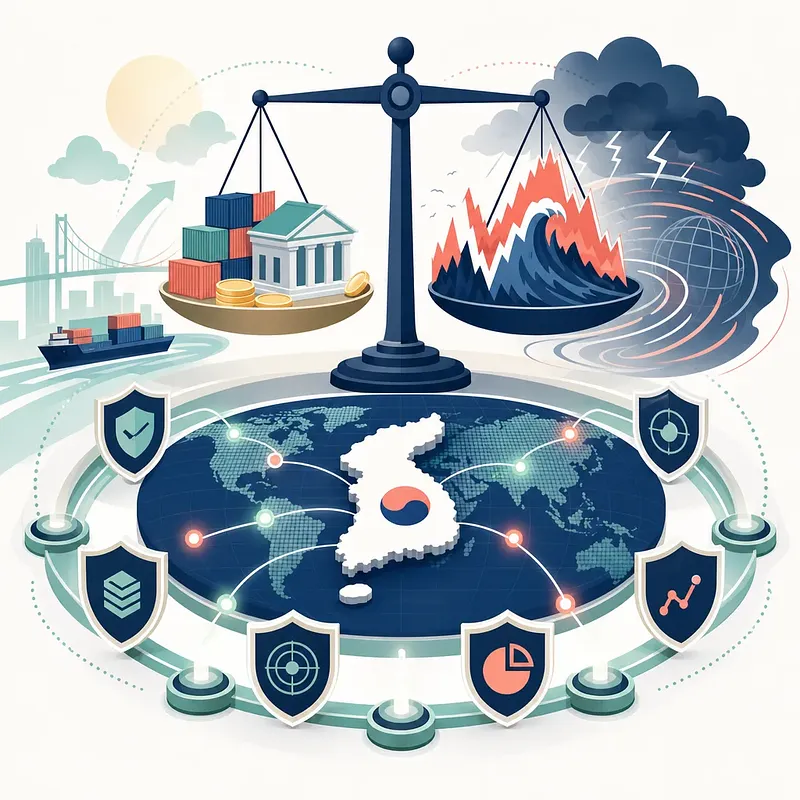
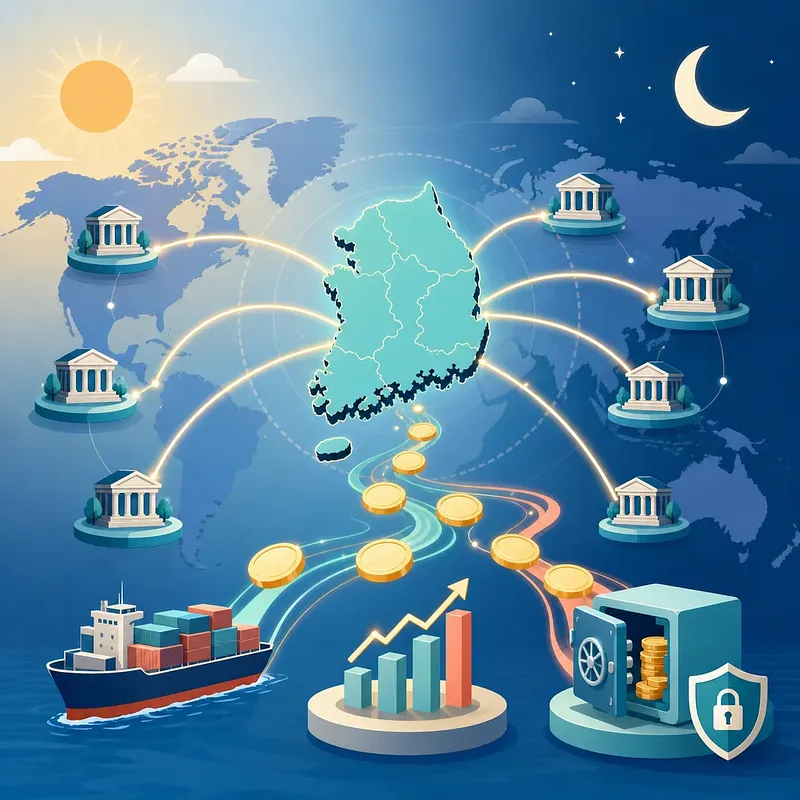
Korea’s won internationalization roadmap is designed to expand how the currency can be used outside the country. The central measure would allow foreigners to open won accounts at registered overseas financial institutions and use them for payments, remittances, and investments. A pilot is scheduled for September 2026, with full implementation and an offshore settlement network planned for 2027. This could simplify settlement for foreign investors and help exporters reduce exchange costs and currency risk. However, internationalization also requires safeguards. Certain transactions will retain reporting obligations, overseas institutions must qualify to participate, and expanded 24-hour trading could increase exchange-rate volatility and accelerate the transmission of external shocks. The article explains both the expected benefits and the risks policymakers will need to manage. Read more : https://injoys.com/en/articles/korean-won-internationalization-roadmap #WonInternationalization #ForeignExchange
The national real estate policy debate outlined potential changes that could affect property owners, investors, and housing supply timelines. Key proposals included differentiated holding taxes based on ownership and occupancy, possible limits on capital gains tax relief for single-home owners, and a temporary off-ramp for multi-home owners who sell properties. The supply discussion prioritized shortening compensation, approval, and construction commencement processes at existing public housing sites rather than designating additional sites. Why it matters: none of the tax rates, price thresholds, loan restrictions, or implementation measures is final. Future tax reform proposals, legislative amendments, and regulations will determine the actual impact. Read more : https://injoys.com/en/articles/korea-housing-policy-tax-supply-debate #RealEstatePolicy #HousingSupply
Financial Income and Health Insurance Premiums: Criteria for Employee Subscribers, Local Subscribers, and Dependents
Financial income can have substantially different health insurance consequences depending on subscriber status. Employee subscribers are generally assessed an additional monthly premium when annual non-salary income exceeds ₩20 million. For local subscribers, annual interest and dividend income above ₩10 million may result in the full amount being reflected—not merely the excess. The distinction also matters for ETF investors: taxable gains from domestically listed ETFs investing overseas are generally treated as dividend income, while gains from overseas-listed ETFs are treated as capital gains. This article outlines these rules, the potential role of an ISA, and the income, asset, business-income, and deadline checks relevant to dependent status and voluntary continuation coverage. #HealthInsurance #FinancialPlanning