 OnBinder
Social
A short written take on each piece of content: what changed and why it matters. Skim the point first, then follow through to the full article only for what interests you. Every take is drawn from real content, so the link takes you straight to the material it is based on.
Calculating Comprehensive Real Estate Tax for Married Couples Under the 2026 Tax Reform Proposal
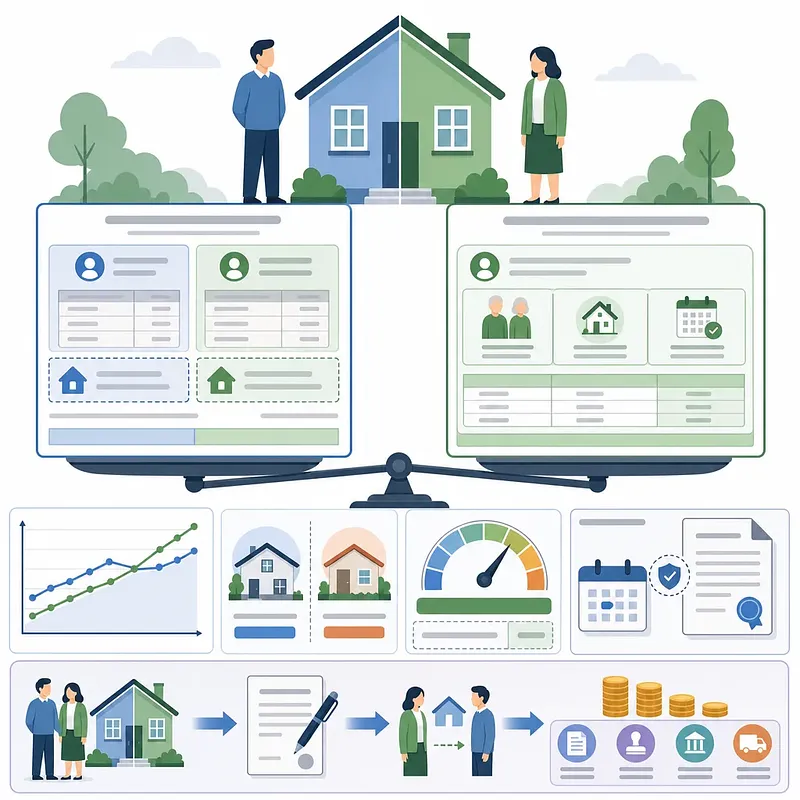
For married couples who jointly own one home, selecting a Comprehensive Real Estate Tax method requires more than comparing basic deductions. Under the proposed 2026 reform, the outcome could vary with actual occupancy, officially assessed value, homeowner age, holding period, and tax credit limits. Individual taxation may be more favorable at lower values, the special provision may provide an advantage in the middle range for eligible senior or long-term owners, and credit limits may shift the balance again for high-value homes. The article also clarifies that choosing a tax method is separate from changing registered ownership. Transferring a share solely for tax reasons can introduce gift tax, acquisition tax, and registration expenses. Because this is a proposal rather than finalized legislation, taxpayers should verify the applicable law and National Tax Service guidance. #RealEstatePolicy #Taxes
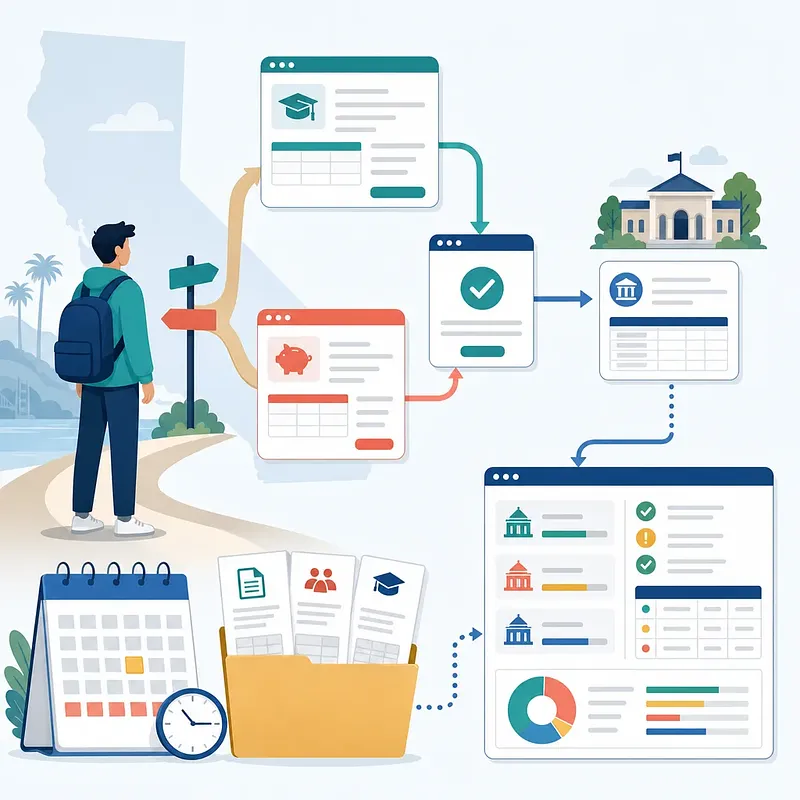
California community college students pursuing additional Cal Grant consideration for 2026–27 should plan around the September 2, 2026 application deadline. The process starts with determining whether the FAFSA or California Dream Act Application applies to your circumstances. Students should gather 2024 income and tax records, household information, and details about their intended college before filing. Submission is only one part of the process. It is also important to confirm that a Cal Grant GPA was electronically reported and to review school, GPA, and award eligibility information through WebGrants 4 Students. The article outlines each step and explains how to identify and correct errors. #CalGrant #FinancialAid
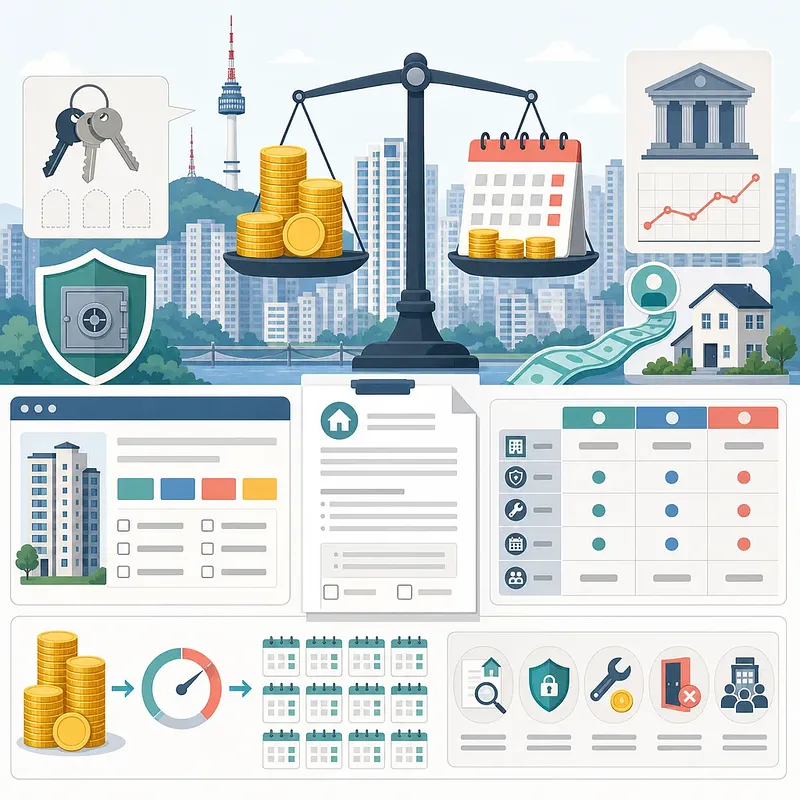
Seoul’s rising share of monthly rental transactions points to a structural change shaped by fewer jeonse listings, shifting financial conditions, deposit repayment risks, and landlords’ preference for recurring cash flow. Understanding the data requires care: the monthly-rent share describes newly reported contracts, not the proportion of all tenant households currently living under monthly-rent arrangements. The article also explains conversion-rate calculations. At a 5.6% annual rate, converting a 100 million won deposit produces a monthly equivalent of approximately 467,000 won. It distinguishes market conversion rates from the statutory ceiling and outlines key contract checks, including deposit protection, fees, termination clauses, and ownership information. #HousingMarket #HousingCosts
2026 Rita Cetina Primary School Support: Checking a Missing Payment and Preparing for the Next Application
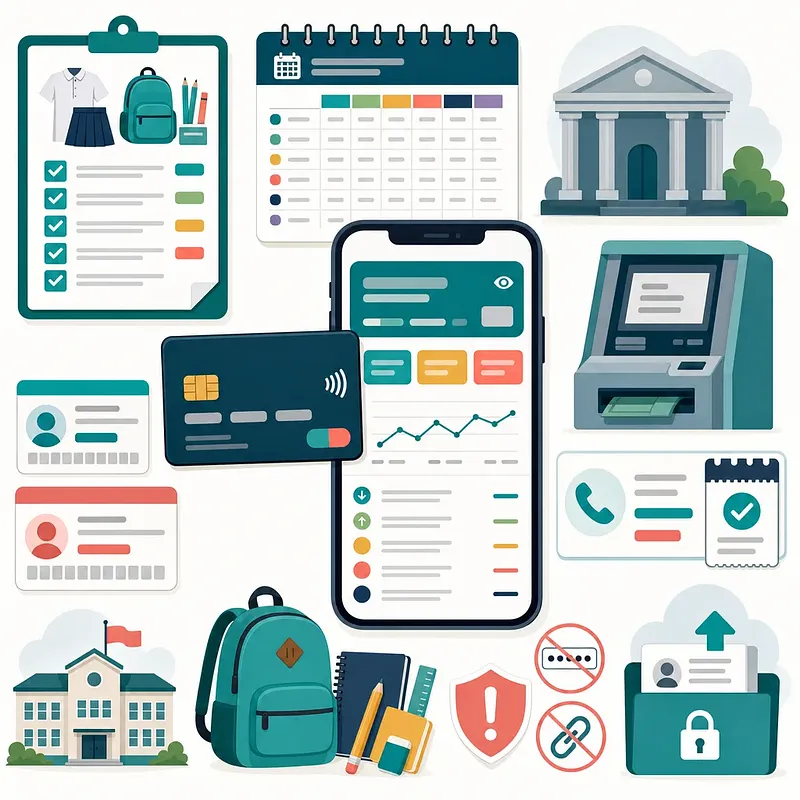
A missing school-support deposit can create uncertainty for families preparing for a new term. For the August 2026 Rita Cetina primary school uniform and supplies support, verification should begin with the student’s approval status, the official surname-based payment schedule, and the Banco del Bienestar card balance. If no deposit appears, organized records can make follow-up easier. Families should have the student’s CURP, registration folio, school information, the card’s last four digits, and evidence of prior checks ready before contacting 079 or the scholarship service desk. Keeping the reference number is also important. This guide also outlines what guardians can prepare—including Llave MX and required documents—before the next application announcement. #RitaCetina #EducationSupport
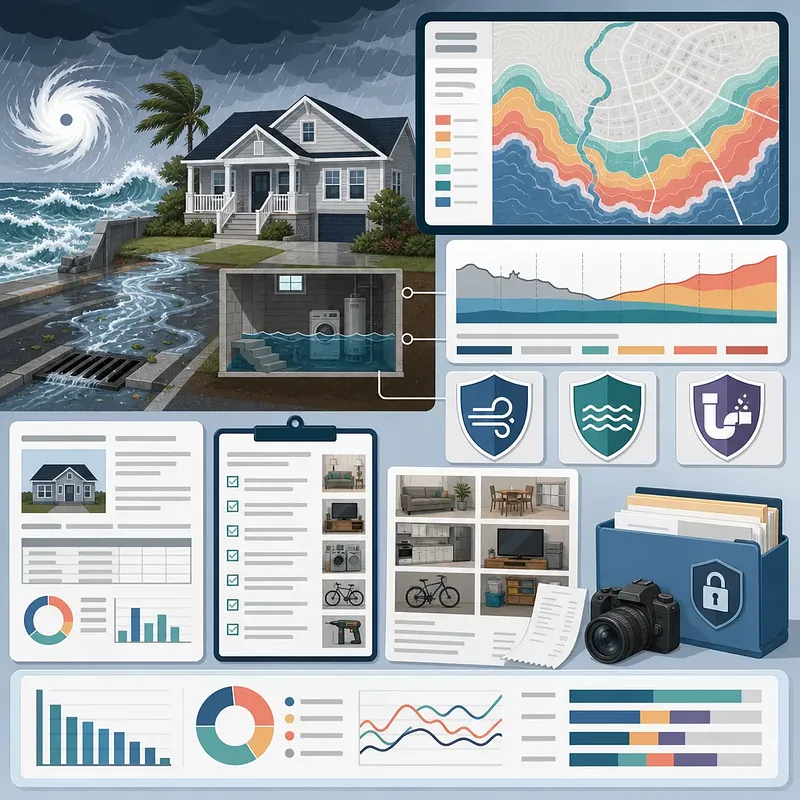
FEMA flood maps provide a valuable baseline for evaluating property risk, but they should not be treated as a complete assessment. Homes outside a Special Flood Hazard Area can still flood because of intense rainfall, inadequate drainage, sewer backups, surface runoff, storm surge, or outdated mapping. Before hurricane activity peaks, homeowners can strengthen their preparation by checking address-specific flood zones alongside elevation, previous flood history, and coastal exposure. It is also important to understand the distinctions among homeowners, windstorm, and flood insurance—especially because storm surge is generally classified as flooding. Pre-storm photos, videos, inventories, receipts, serial numbers, and policy records can provide essential evidence if a claim becomes necessary. #FEMA #FloodRisk #DisasterPreparedness
8.13 Three-Part Youth Housing Support Package: Homeownership, Semi-Jeonse, Jeonse, and Risks to Check
Korea’s August 13 proposal introduces three forms of youth housing finance support: a homeownership loan, a combined guarantee for semi-jeonse and monthly rent, and expanded special youth jeonse loan guarantees. For prospective buyers, the distinction between policy benefits and property risk matters. The proposed Youth Future Bogeumjari Loan targets people aged 39 or younger with annual income of KRW 70 million or less who buy qualifying non-apartment homes priced at KRW 400 million or less. However, the interest rate, LTV margin, fees, income calculation, and application process remain subject to final announcements. The article reviews proposed eligibility, an illustrative repayment calculation, and essential due diligence for non-apartment purchases. #HousingPolicy #RealEstate