 OnBinder
Social
A short written take on each piece of content: what changed and why it matters. Skim the point first, then follow through to the full article only for what interests you. Every take is drawn from real content, so the link takes you straight to the material it is based on.
The July 2026 U.S. Producer Price Index offered encouraging—but limited—evidence of easing inflation pressure. Final-demand PPI rose 4.7% year over year and was unchanged month over month, while core PPI increased 4.2% annually and 0.2% monthly. Why does this matter? A lower-than-expected reading may reduce pressure for further rate increases, but it does not establish a timetable for Federal Reserve rate cuts. PPI also does not lead CPI by a fixed interval: item composition, business margins, import prices, and base effects can alter how producer costs reach consumers. The article explains how to interpret the figures alongside employment, PCE inflation, and financial conditions. #Inflation #MonetaryPolicy #Fed
Financial Counseling for All Young Adults: Eligibility, Process, and Preferential Rates
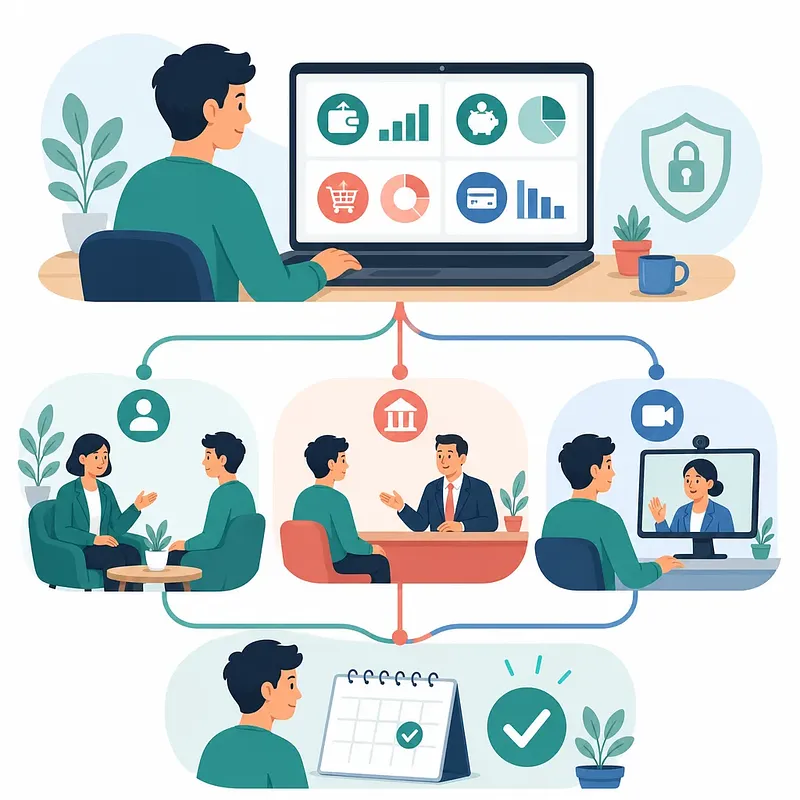
Young adults ages 19–34 can receive one-on-one financial counseling designed around their income, assets, debt, and financial goals. The process begins with an online financial assessment, followed by a choice of outreach counseling, financial institution counseling, or an online session. This matters because the program goes beyond general guidance: counselors can help create practical plans for budgeting, saving and investing, credit, and debt management. A follow-up session about one month later reviews progress and identifies any need for employment or welfare support. The article also outlines the conditions for a 0.2 percentage-point preferential rate on the Youth Future Savings Account, including the counseling completion deadline relative to maturity. #FinancialCounseling #YouthFutureSavings
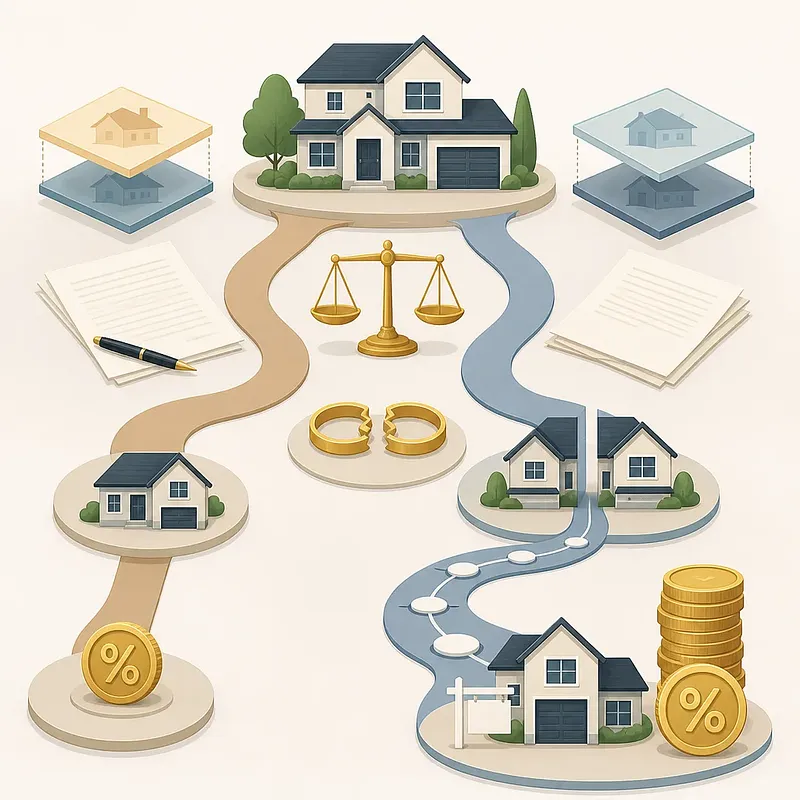
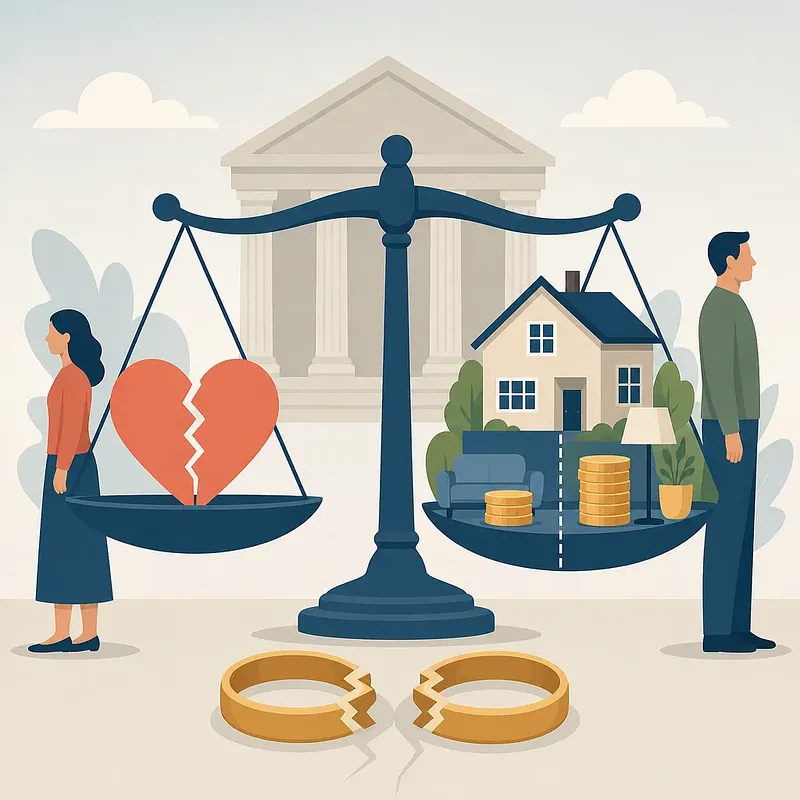
The distinction between divorce damages and property division matters beyond the wording of a settlement. Damages compensate for harm caused by conduct that contributed to the marriage’s breakdown. Property division, by contrast, allocates assets accumulated through the spouses’ respective contributions—and may still be claimed by an at-fault spouse. When real estate is involved, the classification can affect capital gains tax at transfer, acquisition tax, and the acquisition date and cost carried into a later sale. Authorities may examine the marriage’s duration, how assets were built, the division ratio, and the payment’s actual purpose rather than relying solely on its label. #PropertyDivision #TaxPlanning
Gyeonggi Province Declares Fiscal Emergency: KRW 770 Billion in Cuts and Revenue Structure Analysis
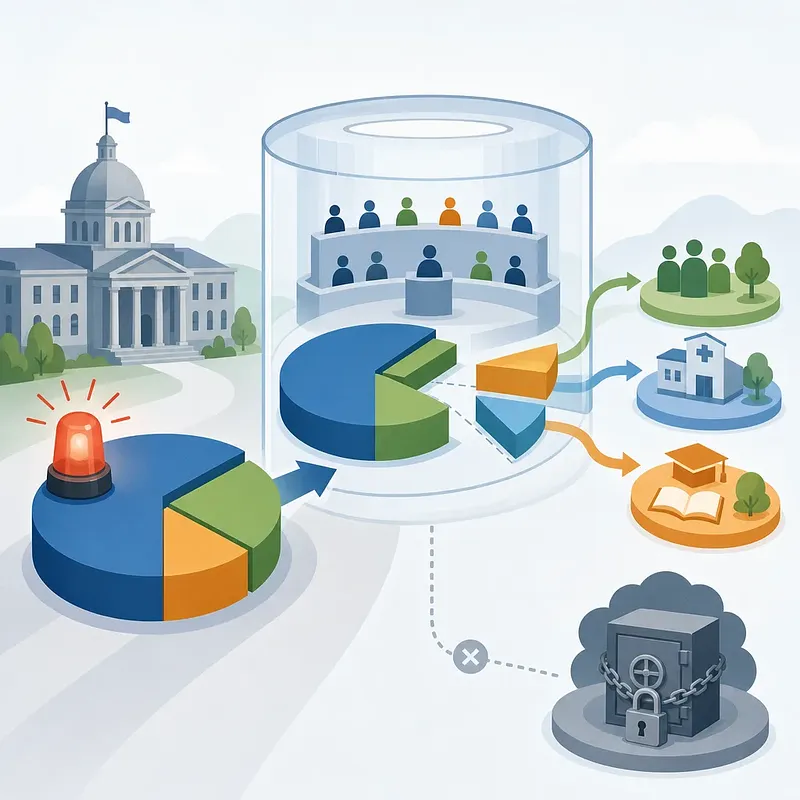
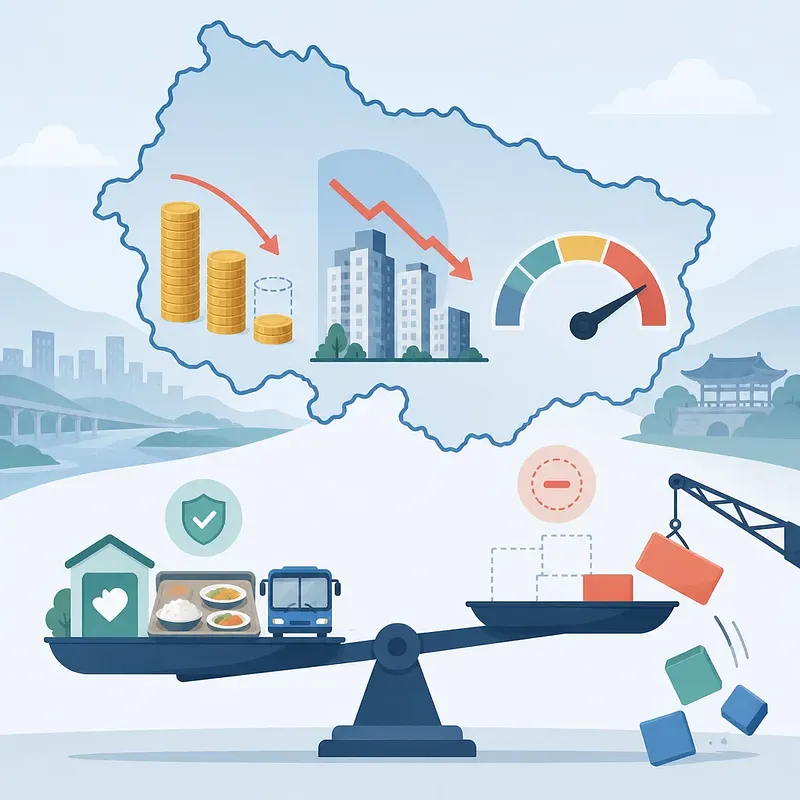
Gyeonggi Province’s fiscal emergency declaration highlights the pressure that declining transaction-based tax revenue can place on local government budgets. Acquisition tax revenue reportedly fell from KRW 11 trillion in 2021 to KRW 7.8 trillion in 2025, while local bond issuance reached 99.6% of the applicable limit in 2025. The announced KRW 770 billion reduction is an overall budget-cut target, not the same as the KRW 313.2 billion fourth-quarter shortfall for livelihood programs. The declaration is also administrative and should not be confused with a fiscal-crisis designation under the Local Finance Act or insolvency. The practical impact will depend on the supplementary budget and Gyeonggi Provincial Council deliberations. #LocalGovernmentFinance #GyeonggiProvince
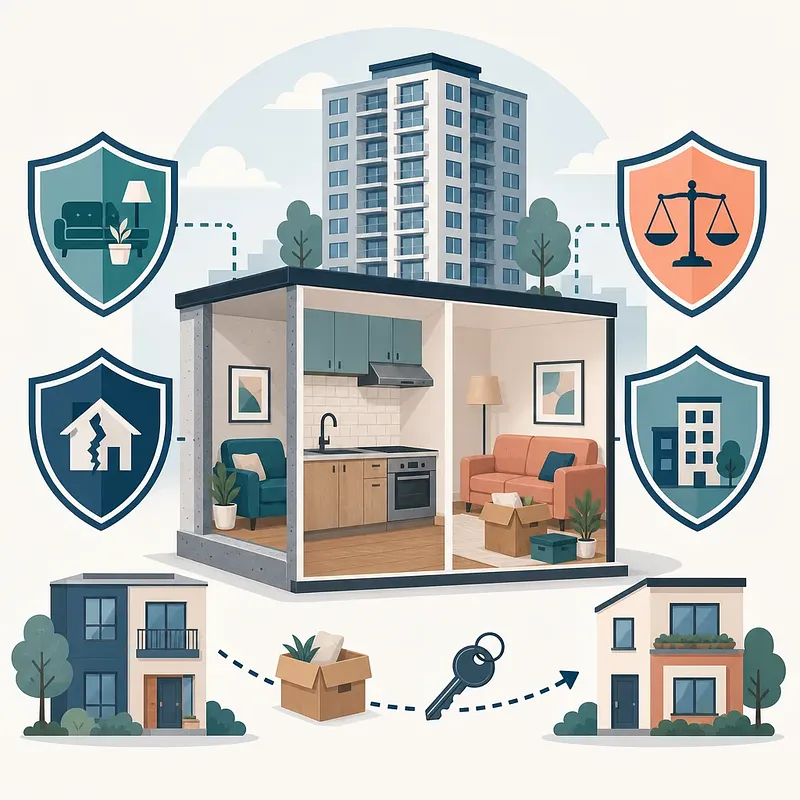
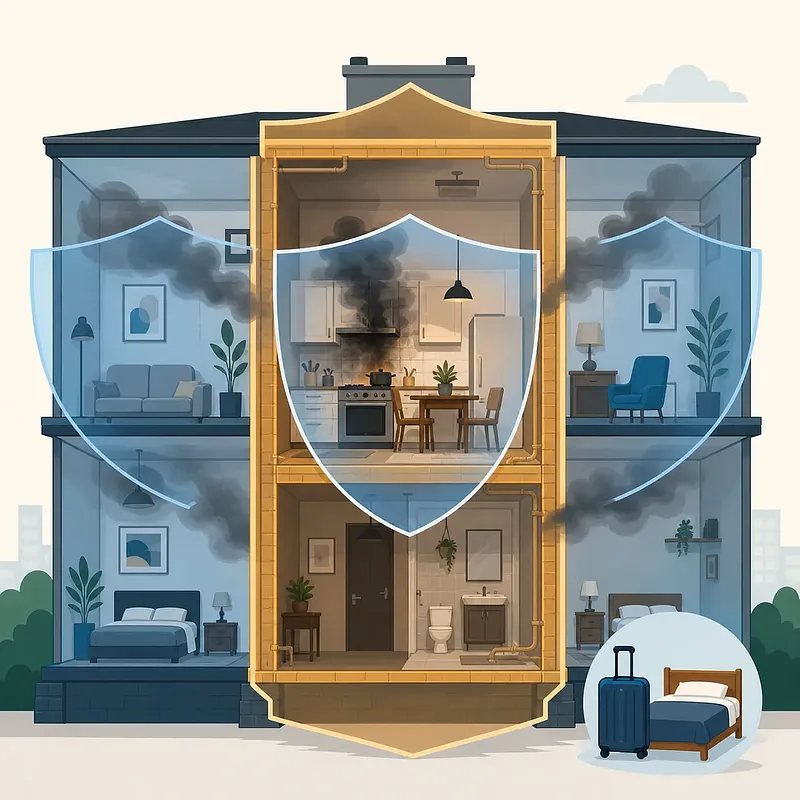
Fire insurance responsibilities can be easy to misunderstand in a rental property. Although tenants are generally not legally required to hold personal home fire insurance, a lease may impose that requirement—and the landlord’s policy primarily protects the building owner’s losses. Tenants should assess coverage for belongings, temporary accommodation, liability to the landlord, and liability for damage to neighbors. Group insurance for apartment buildings of 16 or more floors also warrants a closer look at insured amounts, covered parties, deductibles, and in-unit protection. Policyholders should also notify the insurer when moving or when the property’s use, structure, address, or risk information changes. #RentersInsurance #RiskManagement
Understanding the Structure of the Yen, Won, and Dollar Through the History of Currency Intervention
Exchange-rate analysis becomes misleading when it relies on interest-rate differentials alone. Policy expectations, global dollar movements, trade balances, foreign capital flows, risk aversion, inflation, and growth prospects can all operate at the same time. Japan’s experience is instructive: dollar-selling and yen-buying intervention resumed in 2022, so describing a later action as the first such intervention in 28 years is inaccurate. Intervention may limit short-term volatility, but sustaining a reversal generally requires support from broader economic fundamentals. The article uses this history to clarify the Bank of Japan’s dilemma, the multiple drivers of the won-dollar exchange rate, and a practical approach to managing dollar or yen exposure through timing, loss limits, and phased exchanges. #MonetaryPolicy #ExchangeRates