 OnBinder
Social
A short written take on each piece of content: what changed and why it matters. Skim the point first, then follow through to the full article only for what interests you. Every take is drawn from real content, so the link takes you straight to the material it is based on.
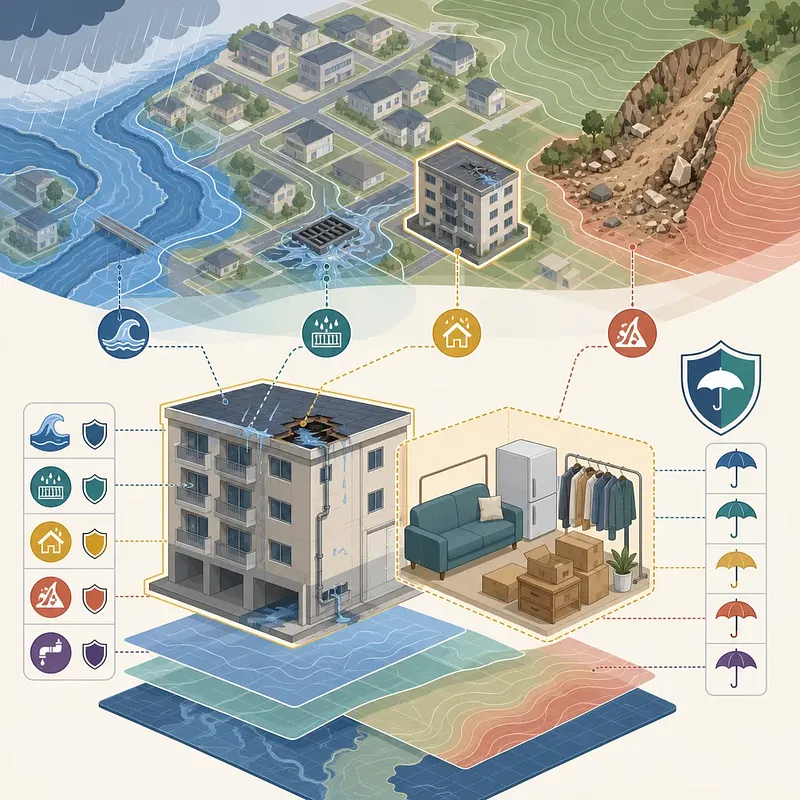
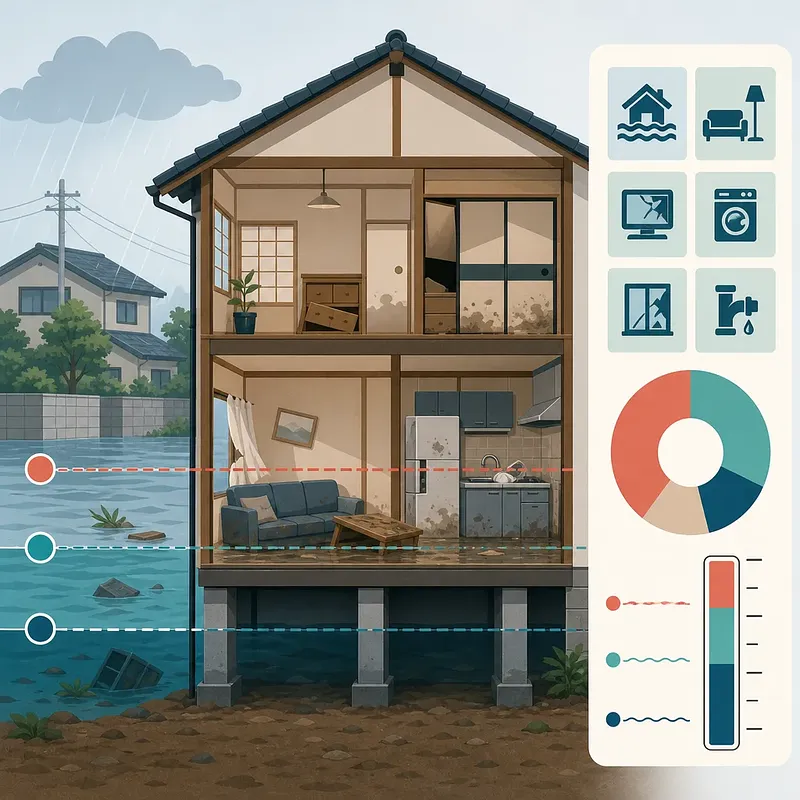
Understanding flood coverage in Japanese fire insurance requires more than checking whether an area appears on a hazard map. Policies may use distinct conditions such as inundation exceeding 45 cm from ground level, flooding above floor level, or a loss ratio of at least 30%—but the actual contract terms take precedence. This article explains why projected inundation depth indicates future risk rather than claim eligibility, and how river flooding, inland flooding, rainwater intrusion, and water leakage may be treated differently. It also outlines the separate checks renters should make for household contents, tenant liability, and repair expenses. #JapaneseInsurance #FloodRisk #RiskManagement
How to Interpret and Prepare for Simultaneous Rises in Home Prices, Jeonse, and Monthly Rents
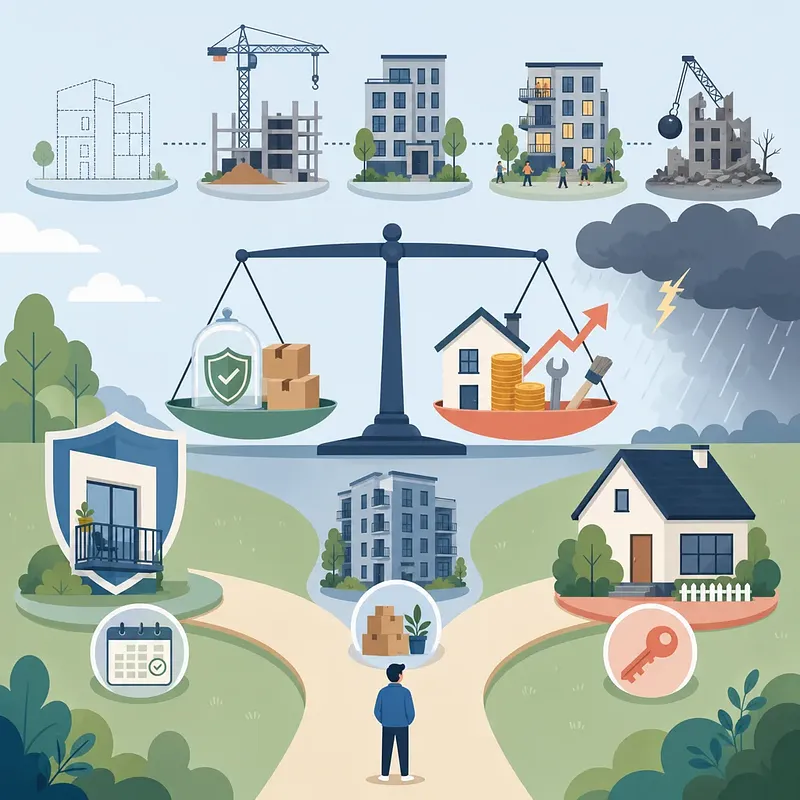
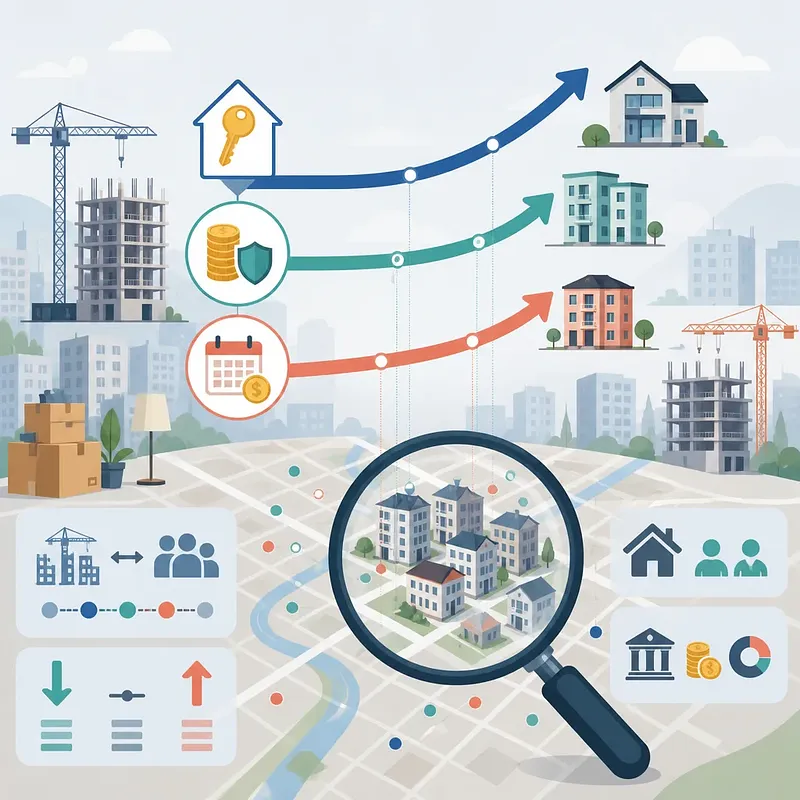
Simultaneous increases in home prices, jeonse, and monthly rents can occur because these housing options function as substitutes. However, attributing every local increase to a supply shortage can lead to poor decisions. A more useful assessment combines actual transaction prices, rental volumes, listing time on market, future move-in supply, interest rates, and household numbers within the relevant living area. It also distinguishes permits, construction starts, completions, and move-ins rather than treating them as interchangeable supply measures. For renters, preparation should begin 4–6 months before lease expiry. For prospective buyers, affordability should be stress-tested against higher rates, declining income, and lower prices—not inferred from a high jeonse-to-sale ratio alone. #HousingMarket #HousingSupply
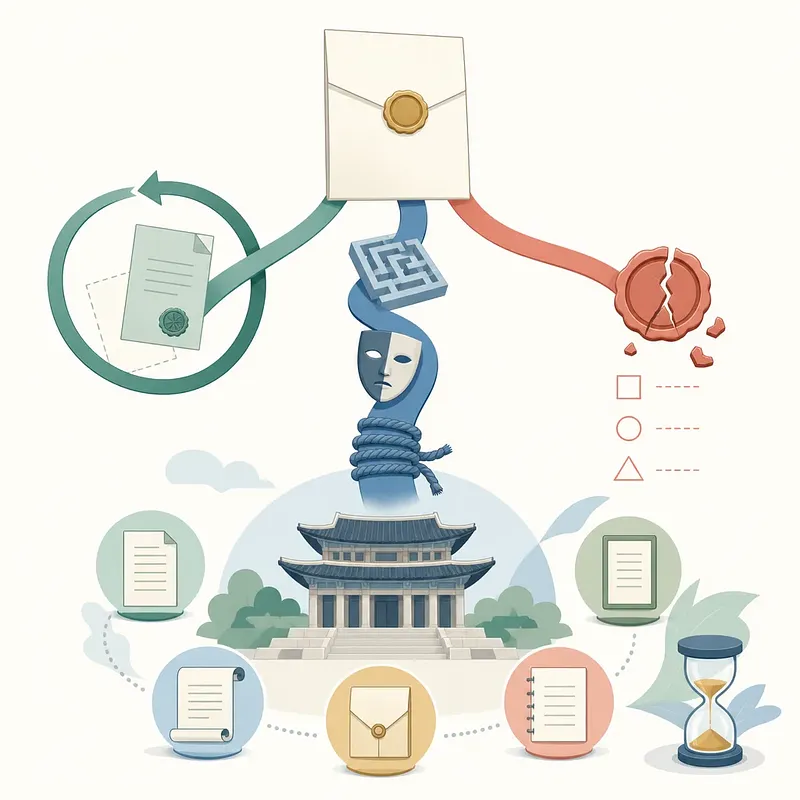
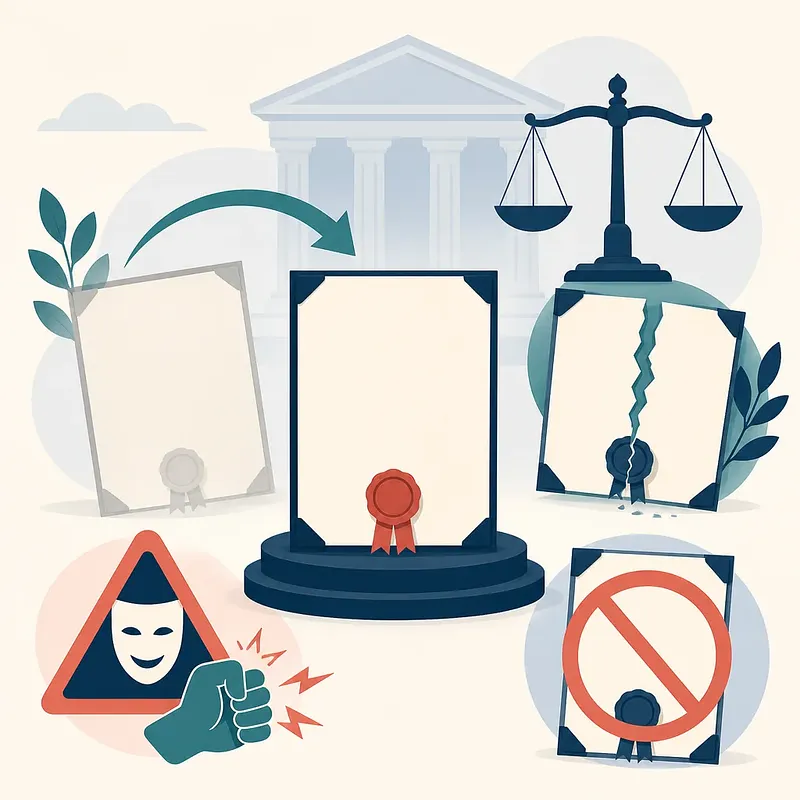
The legal effect of a will in South Korea depends on more than the testator’s written wishes. Under the Civil Act, a testator may freely revoke all or part of a will before death, including through a later will or an inter vivos act. Conflicting terms in a newer will can revoke earlier provisions to the extent of the conflict. This article also distinguishes revocation from cancellation and invalidity. It outlines when mistake, fraud, or duress may permit cancellation, why the applicable exclusion period must be reviewed, and how failure to follow one of the five statutory forms can make a will invalid. Testamentary age and mental capacity are also essential considerations. Understanding these distinctions can help families and professionals assess whether a will remains legally effective. #Inheritance #CivilLaw
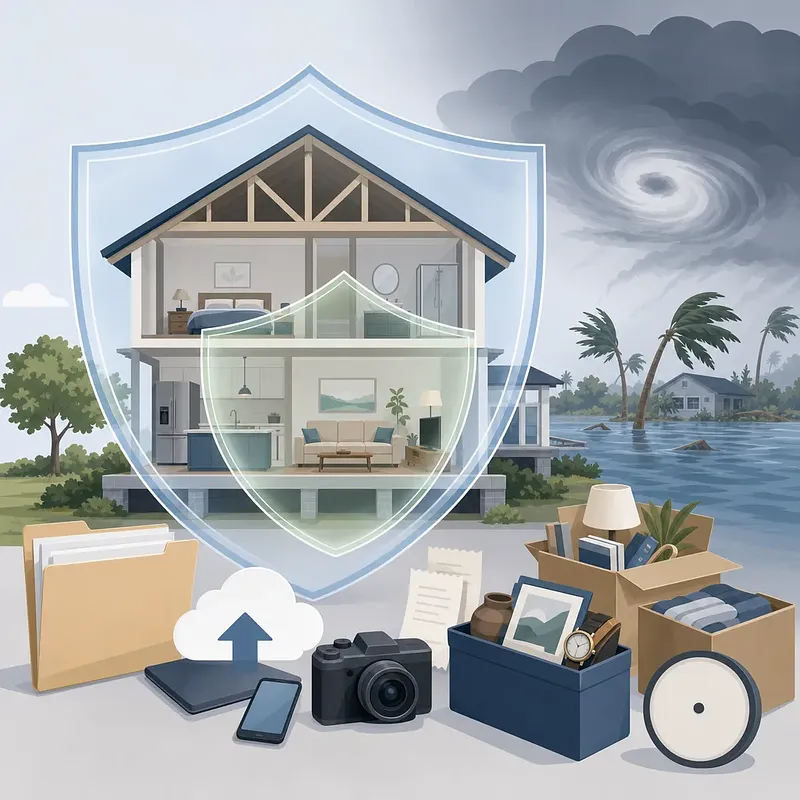
Hurricane losses often involve more than one insurance policy, making the cause of damage especially important. Standard homeowners insurance generally does not cover storm surge or rising surface water. However, rain entering after wind damages a roof or window may be covered by homeowners insurance or a separate windstorm policy. NFIP policyholders should also verify building and personal property coverage separately, including the limits for each. New NFIP policies generally have a 30-day waiting period, subject to limited exceptions. Reviewing coverage and storing policies, inventories, photos, videos, and receipts externally can make future claims easier to document. #FloodInsurance #NFIP #DisasterPreparedness
Spain’s MEC scholarship repayment rules vary according to the program and the reason for review. University students who complete less than 50% of enrolled credits generally face a repayment review, with a 40% threshold for science and technology fields. Non-university students may be reviewed for attending less than 80% of class hours without a valid reason or passing less than 50% of enrolled subjects, credits, or hours. The distinction matters because tuition support is explicitly excluded when repayment results from insufficient completion, while canceled enrollment and de facto withdrawal are assessed separately. Students should compare the relevant year’s scholarship announcement with the official notice and never transfer funds without an authorized payment form. #MECScholarship #ScholarshipRepayment
How to Compare Apartment Management Fees 1-to-1 on K-apt Before a Fall Move
Apartment management fee comparisons can be misleading when the underlying properties are not truly comparable. K-apt’s 1-to-1 feature helps prospective renters and buyers compare two complexes using the same billing month and per-unit cost categories. For a useful comparison, select similar unit sizes and distinguish common management fees, individual usage charges, and long-term repair reserves. Context matters: heating type, number of units, and year of completion can affect totals. Since K-apt reports complex-wide averages, review 12 months of trends, compare nearby complexes, and request the actual bills for the unit before signing. #HousingCosts #Kapt